Self-Managed Financial Planning: A DIY Framework for Organizing Your Finances
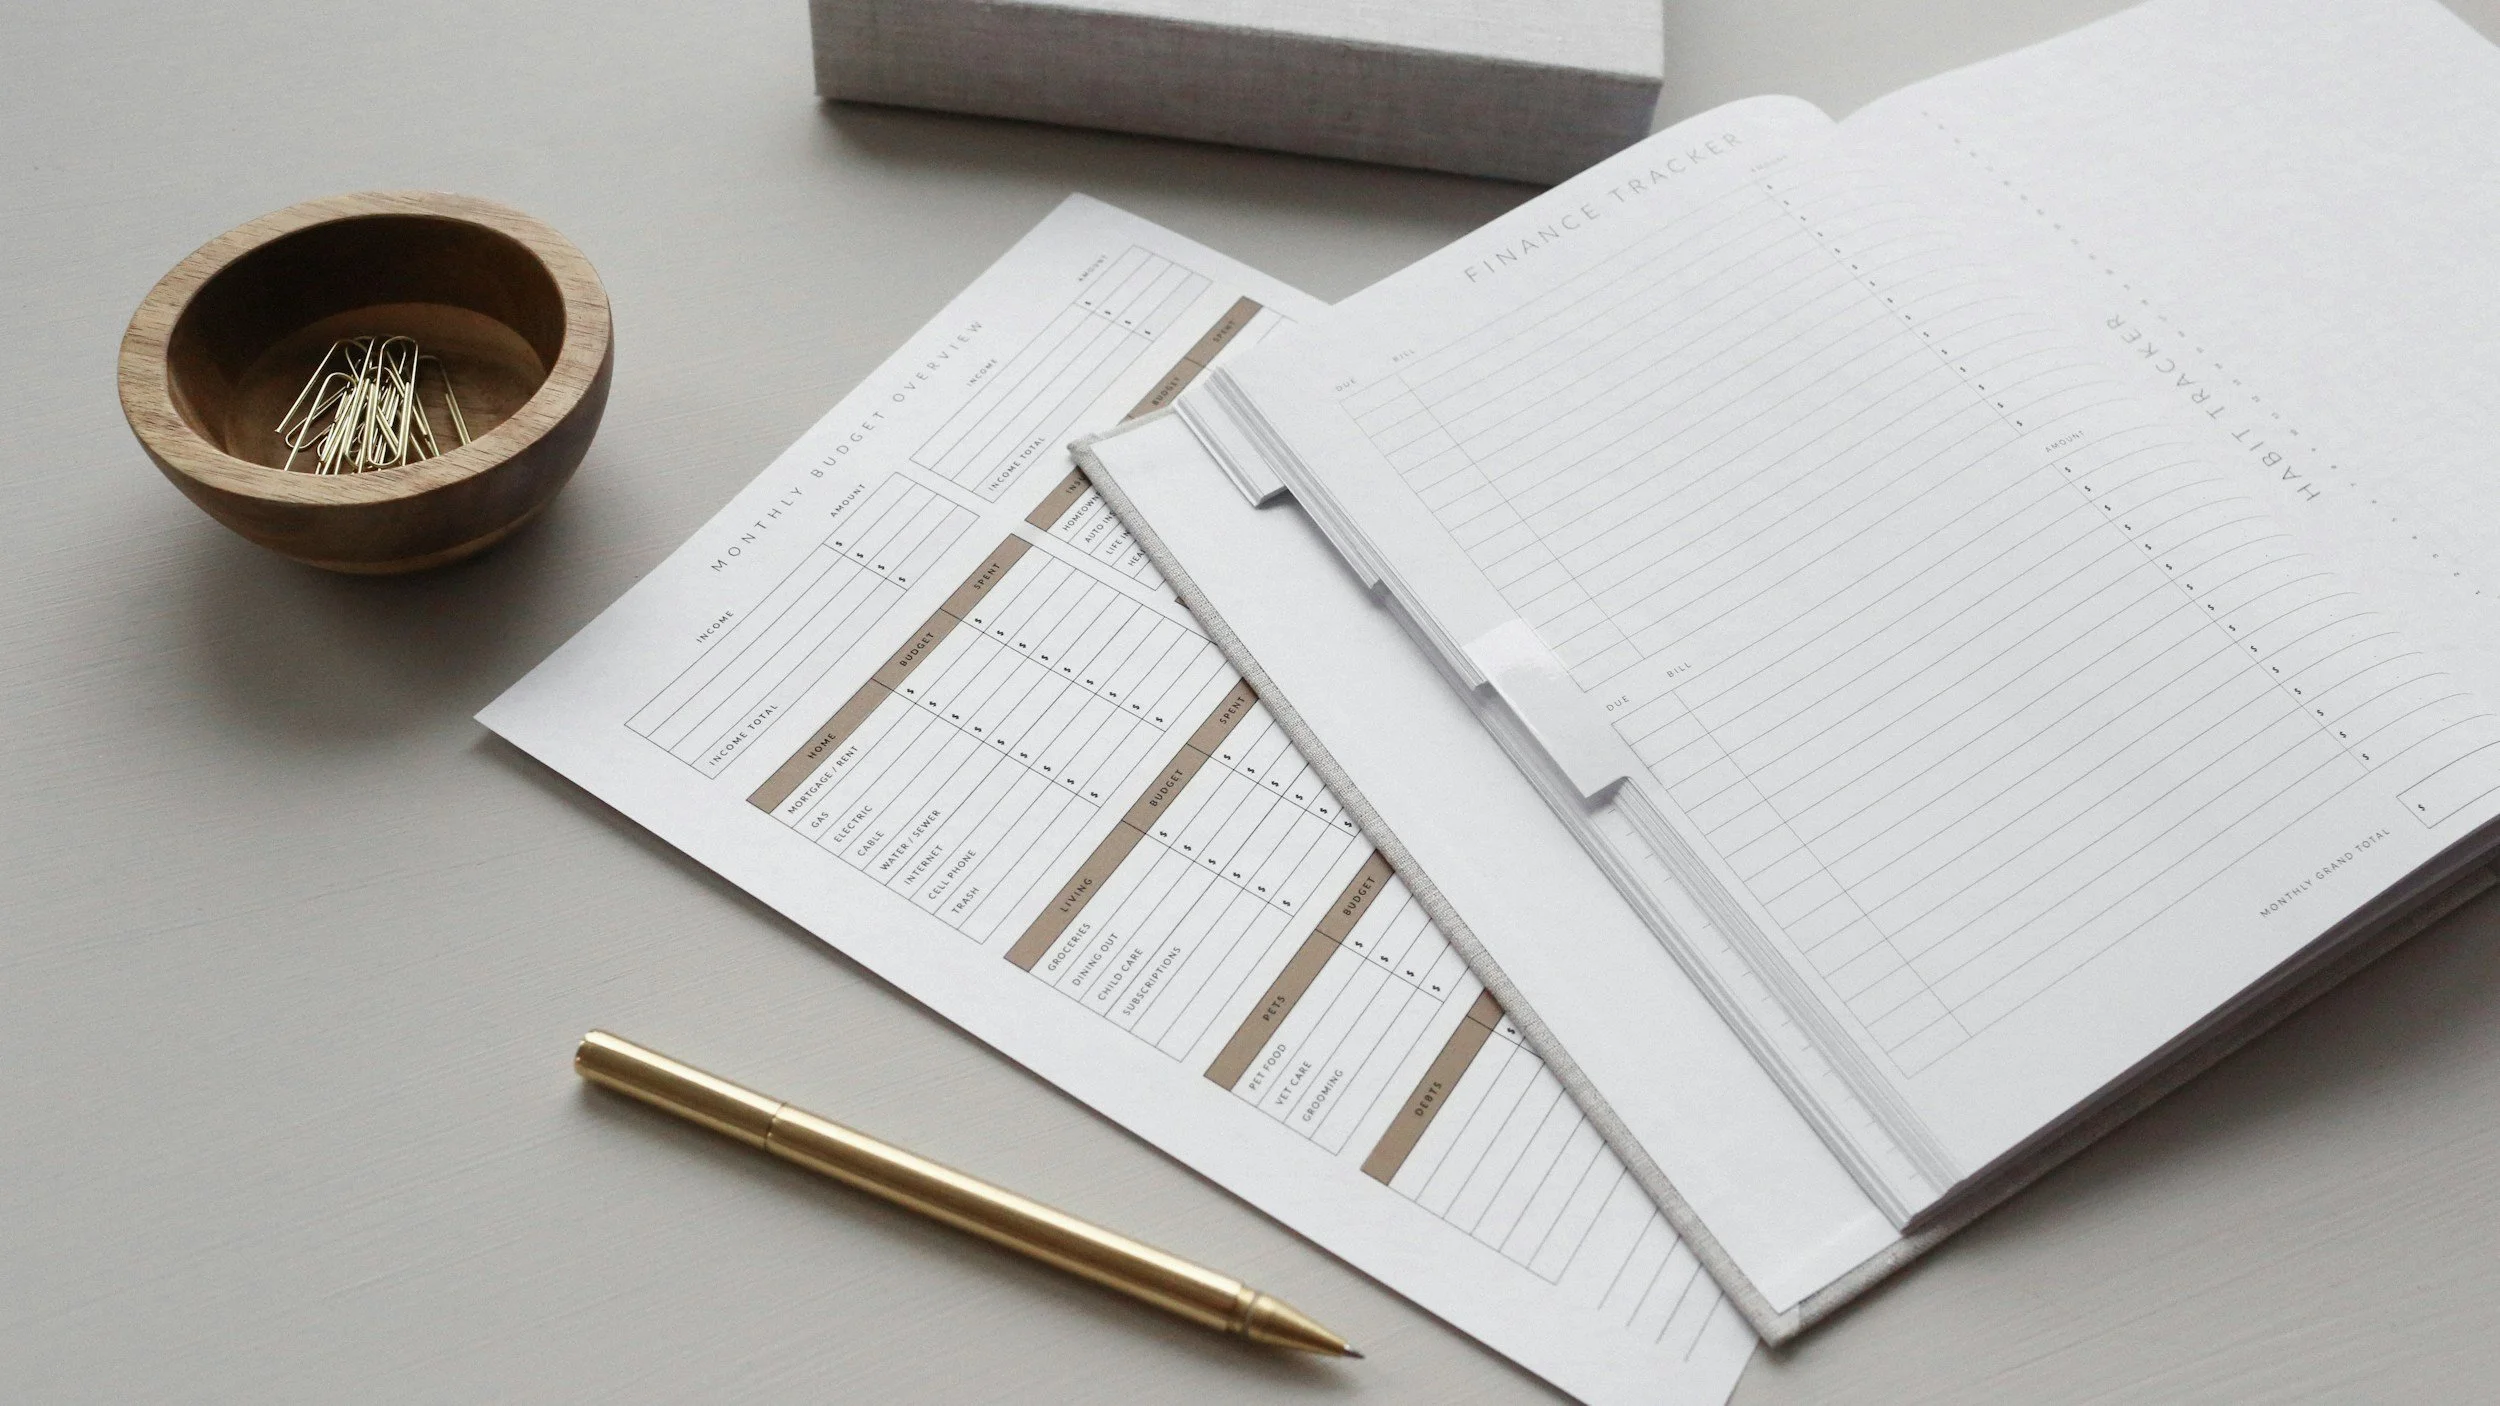
Self-managed financial planning is a do-it-yourself approach to organizing budgeting, saving, investing, insurance decisions, and retirement planning without relying on ongoing professional management. Many people choose this path because they want more involvement and clarity in financial decisions.
This approach does not require doing everything alone. Many households combine personal decision-making with tools, education, and occasional professional input. The goal is to maintain structure while keeping decisions manageable and consistent over time.
What self-managed financial planning typically includes
A self-managed approach often covers:
Cash flow tracking: income, essential expenses, and savings rate
Emergency reserves: liquidity for unexpected expenses
Debt planning: prioritizing repayment strategies
Investment planning: asset allocation and ongoing monitoring
Retirement contributions: planning and contribution tracking
Insurance review: coverage for life, disability, and property
Tax awareness: understanding how decisions affect tax outcomes
Estate basics: updating beneficiaries and key documents
The appropriate level of complexity depends on goals, income stability, and available time.
A 7-step DIY framework
1. Set clear goals
Examples include building an emergency fund, contributing to retirement accounts, or saving for a home.
2. Build a cash flow view
Track income after taxes, essential expenses, discretionary spending, and savings capacity.
3. Establish an emergency fund
Start small and build toward a target based on household stability and expenses.
4. Match accounts to goals
Use short-term accounts for liquidity and tax-advantaged accounts for long-term planning, subject to eligibility rules.
5. Select an investment approach
Many DIY investors use diversified, low-cost portfolios aligned with time horizon and risk tolerance. All investing carries risk.
6. Rebalance periodically
Review allocations on a schedule rather than reacting to short-term market news.
7. Track key metrics
Monitor savings rate, retirement contributions, debt reduction, and tax deadlines.
Common mistakes in DIY planning
Underestimating tax impacts from income or investment changes
Overcomplicating investment portfolios with overlapping funds
Not updating beneficiaries after life changes
Skipping insurance reviews after major events
Delaying adjustments during transitions like job changes or relocation
When outside support may help
Some situations can benefit from guidance, including:
Multiple income sources or higher income households
Business ownership or contractor income
Equity compensation or stock-based pay
Major life events affecting tax or estate needs
Many people still stay in control of decisions while using outside input to review assumptions and clarify tradeoffs.
Where Compound Wealth may fit
For those building a self-managed plan, structured support can be helpful in reviewing financial decisions and tax considerations. Compound Wealth focuses on planning and tax-related coordination based on publicly available information.
Some individuals use Compound Wealth as a support layer alongside their own planning process, particularly when reviewing assumptions, organizing tax-related decisions, or evaluating financial tradeoffs. This can help keep a self-managed plan more structured over time.
FAQs
1. What is self-managed financial planning?
Self-managed financial planning is a do-it-yourself approach to organizing budgeting, saving, investing, insurance, retirement planning, and tax-related decisions. Some individuals manage these areas independently while seeking professional input for specific questions or more complex decisions.
2. What should I include in a self-managed financial plan?
A basic plan may include cash flow, emergency savings, debt, investments, retirement contributions, insurance, tax considerations, estate documents, and financial goals. The appropriate level of detail depends on the individual's circumstances.
3. How often should I review a self-managed financial plan?
Many individuals review their plans quarterly or annually, as well as after major changes such as a job transition, marriage, home purchase, business ownership, inheritance, or significant change in income.
4. What are common mistakes with DIY financial planning?
Common issues can include overlooking tax implications, failing to update beneficiaries, maintaining excessive investment complexity, underestimating liquidity needs, or delaying financial reviews after major life changes.
5. When might professional guidance be useful with self-managed financial planning?
Outside guidance may be useful when finances involve multiple income sources, business ownership, equity compensation, significant investments, complex tax considerations, or major life transitions. Professional input can also be used selectively to review assumptions or specific decisions.
6. How can I organize my investments as part of a self-managed financial plan?
Investors may start by identifying their goals, time horizons, risk tolerance, account types, and existing asset allocation. Periodic reviews can help identify whether the portfolio remains aligned with those factors.
7. How should taxes fit into DIY financial planning?
Tax considerations can affect investment decisions, retirement contributions, charitable giving, business income, and other financial choices. Reviewing potential tax implications before making significant decisions may help provide additional context.
8. Can I combine self-managed financial planning with professional advice?
Yes. Some individuals manage their day-to-day finances independently while using professional guidance for tax planning, investment decisions, business matters, or other areas where additional experience may be useful.
If You Have Any of These Questions, Contact Compound Wealth
How do I know whether self-managed financial planning makes sense for my situation?
What parts of my financial plan should I manage myself versus discuss with a professional?
How can I organize my finances if I have multiple investment and retirement accounts?
What should I review before making a major investment decision on my own?
How can I incorporate tax planning into my DIY financial plan?
What financial planning tasks should I complete each year?
How can I evaluate whether my current investment allocation still fits my goals?
What should I consider if my finances have become too complex to manage on my own?
How can I organize my financial records for a planning review?
How can I coordinate occasional professional guidance with a self-managed financial plan?
What should I review after a major change in income or employment?
How can I account for business ownership in my personal financial plan?
About Compound Wealth
Compound Wealth serves individuals, families, and business owners seeking a coordinated approach to financial planning. By bringing together tax planning, accounting, wealth management, and business transition services, the firm helps clients consider how financial decisions may affect multiple areas of their overall planning strategy.